It does feel slightly uncomfortable. I think a lot of us are going to have to go on a personal journey of some kind when it comes to AI. There's a psychological component about having it do so much for you that we've yet to unpack.
AI
-
Data Volume and Mining Drive Commercial AI Insights
By
–
The driving forces in this brave new world are access to ever-increasing volumes of data and our ever-increasing technological capability to mine that data for commercial insights
-

Refund for AI Content Reactor: Tool Too Powerful for User
By
–
Just sent a guy a refund for AI Content Reactor. It was too powerful. Felt like cheating. Didn't sit right with him. He decided not to use the information. I'll take it as a win.
-

Differential Privacy Results Beyond Pure DP Guarantees
By
–
Everything above is for pure (ε, 0)-DP. We also have results for (ε, δ)-DP. Also, the conversion from robustness to privacy is not always optimal, we have an example for sparse mean estimation. 11/n
-
Robust Gaussian Estimation: Novel Techniques in Statistical Learning
By
–
Finally, see simultaneous work of Alabi, @praveshkkothari
, Tankala, Venkat, Zhang, which also studies private & robust Gaussian estimation from a robust stats perspective. Totally different techniques! https://
arxiv.org/abs/2212.08018 Again, our paper link: https://
arxiv.org/abs/2212.05015 12/12 -
Computational Challenges in Statistical Estimator Implementation
By
–
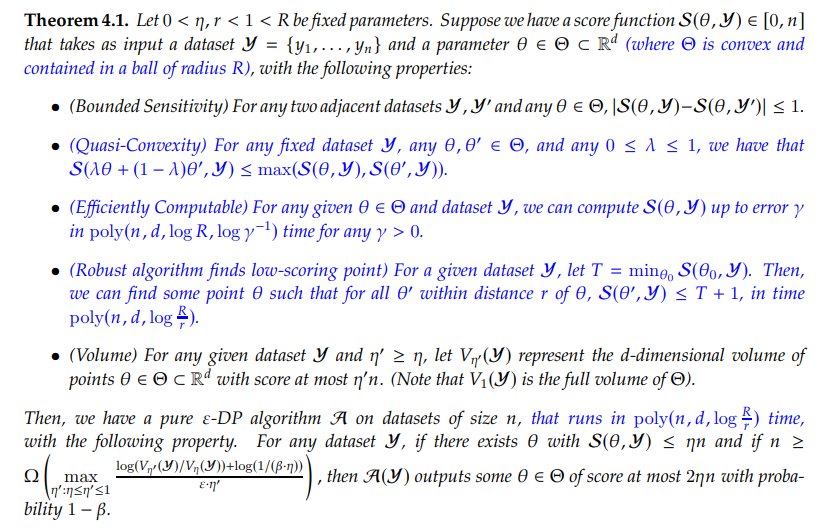
The astute reader will notice I never mentioned computation. Indeed, as stated, it's not clear how to compute this estimator efficiently (or at all!). That's where most of the technical work comes in. I'll leave you with this theorem, check out the rest of the paper. 10/n
-
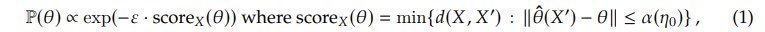
Robust Estimators and Exponential Mechanism for Parameter Scoring
By
–
The notation is a dense, but the algorithm is simple. The score of a parameter vector θ (wrt a dataset) is the minimum number of datapoints that must be changed to make the robust estimator output (approximately) θ. Feed this score into the exponential mechanism. 8/n
-
Private Robust Gaussian Estimation Framework Near-Optimal Sample Complexity
By
–
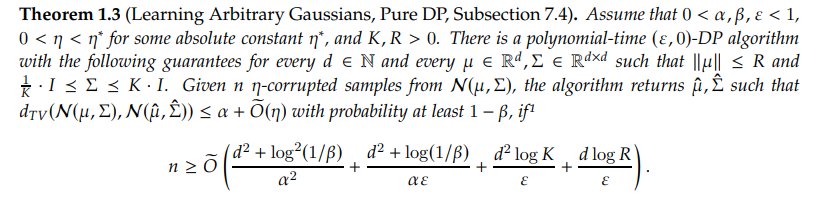
So what can we do with this framework? The most interesting application is estimating Gaussians privately AND robustly: the resulting algorithm nails it, with a near-optimal sample complexity. Other potential applications include mean estimation, regression, etc. 9/n
-
Robust Algorithms Enable Private Algorithm Design
By
–
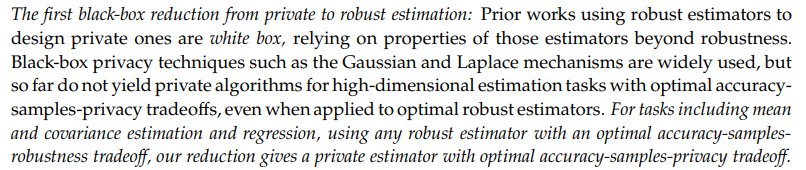
In our work, the main conceptual result shows the other direction: a robust algorithm can be used to design a private algorithm. 7/n
-
Differential Privacy Frameworks for Robust Statistical Estimators
By
–
Most have been instance-specific, e.g., here's a particular robust estimator, let's privatize it. Some have proposed broader frameworks, e.g., https://
arxiv.org/abs/2111.06578 by Liu, Kong and @sewoong79
, or https://
arxiv.org/abs/2112.03548 by @praveshkkothari @pasin30055 @ameya_pa 5/n