AI Dynamics

Global AI News Aggregator

About

@tiernanraytech

  • Humanoid Robots Not Close to Commercialization Despite Hype
    Humanoid Robots Not Close to Commercialization Despite Hype

    There’s a lot of activity around robotics, for sure. None of it points to an inflection. No, even Tesla can’t bring us closer to humanoid robots Hyperbole about humanoid robots being on the cusp of commercialization continues to build. The best research on the matter continues to show otherwise: the most basic technological requirements have yet to be solved, and there is little evidence they will be anytime soon. thetechnologyletter.com $TSLA $WATT $PDYN $SYM $NVDA

    → View original post on X — @tiernanraytech, 2026-03-26 20:51 UTC

  • Micron and SanDisk: Why Investors Should Keep the Faith
    Micron and SanDisk: Why Investors Should Keep the Faith

    I think most investors don’t have a lot of insight about semiconductors per se, and especially not about memory and storage technology, which are experiencing their own renaissance. It is for that reason that we are getting a bunch of panic selling. For Micron, SanDisk, these are not normal times Keep the faith with Micron, SanDisk Morgan Stanley’s Joe Moore defends falling shares of Micron and SanDisk in the face of worries about “demand destruction,” capacity glut, and Google’s “TurboQuant.” He’s right that this cycle is somewhat different than others, in a good way. thetechnologyletter.com $MU $SNDK $GOOGL $NVDA

    → View original post on X — @tiernanraytech, 2026-03-26 19:22 UTC

  • Semiconductor Valuation Disparity: Why KLA and Lam Command Premium Prices
    Semiconductor Valuation Disparity: Why KLA and Lam Command Premium Prices

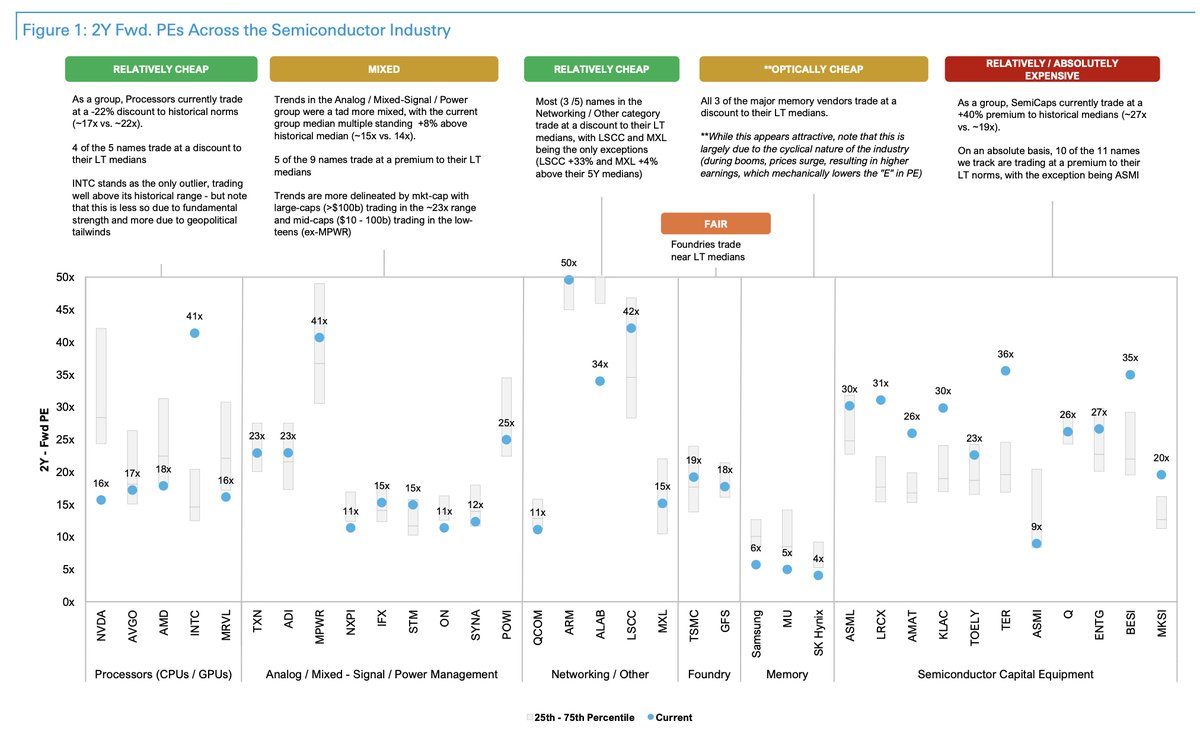
    In an expensive market, we get to nit-picking about what’s really expensive and what’s not… KLA, Lam are pricey for a reason Sometimes the Street ponders why one type of company’s stock is doing better than another. At the moment, the semiconductor stocks are showing the disparity the most, with Nvidia trading below historical valuation and KLA and Lam trading above. As to why, it’s pretty simple: bet on the arms merchants. thetechnologyletter.com $KLAC $LRCX $NVDA

    → View original post on X — @tiernanraytech, 2026-03-25 13:47 UTC

  • CoreWeave’s Path: From Hardware Debt to Software Focus
    CoreWeave’s Path: From Hardware Debt to Software Focus

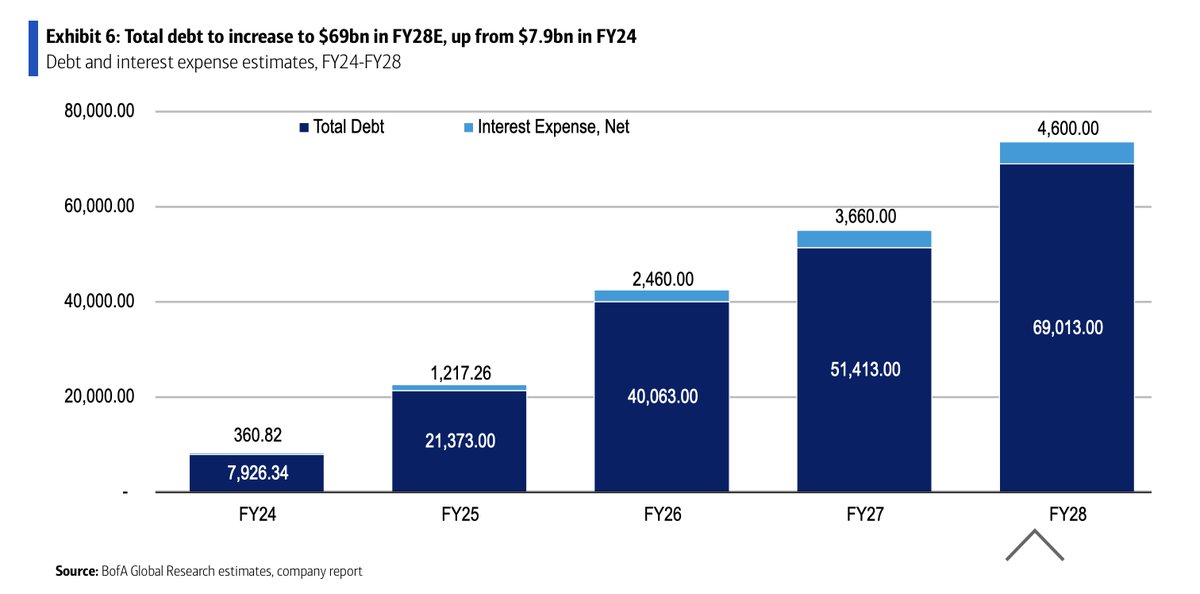
    Pushed into massive spending — $69 billion in debt come 2028, says Merrill — is a kind of enslavement. Maybe there’s a way out… CoreWeave may end up just a software vendor CoreWeave’s “core” strength is software to manage clusters of chips. The company has been pushed into massive borrowing by the urgency of the AI giants. As their support wanes over time, and as the inference market erodes the value in the service, CoreWeave may shed the money-losing part to focus on its software expertise. That would be a good outcome for the company. thetechnologyletter.com $CRWV

    → View original post on X — @tiernanraytech, 2026-03-25 13:43 UTC

  • Software Stocks in Crisis: TWLO, NTNX, DOCN as M&A Candidates
    Software Stocks in Crisis: TWLO, NTNX, DOCN as M&A Candidates

    Everyone is Waiting for Godot, in a sense, with software stocks, something to deliver the group from their misery. M&A is one possibility. Three names stand out as good acquisition candidates. Software bloodbath: TWLO, NTNX, DOCN anyone? Prices and stock valuations keep going lower for software stocks as AI despair sets in. Twilio, Nutanix and DigitalOcean are three names that seem worth a look as potential M&A candidates. $DOCN $TWLO $NTNX thetechnologyletter.com

    → View original post on X — @tiernanraytech, 2026-03-23 20:42 UTC

  • Nvidia’s AI Vision Drives Fiber Optics Opportunity for Lumentum, Coherent
    Nvidia’s AI Vision Drives Fiber Optics Opportunity for Lumentum, Coherent

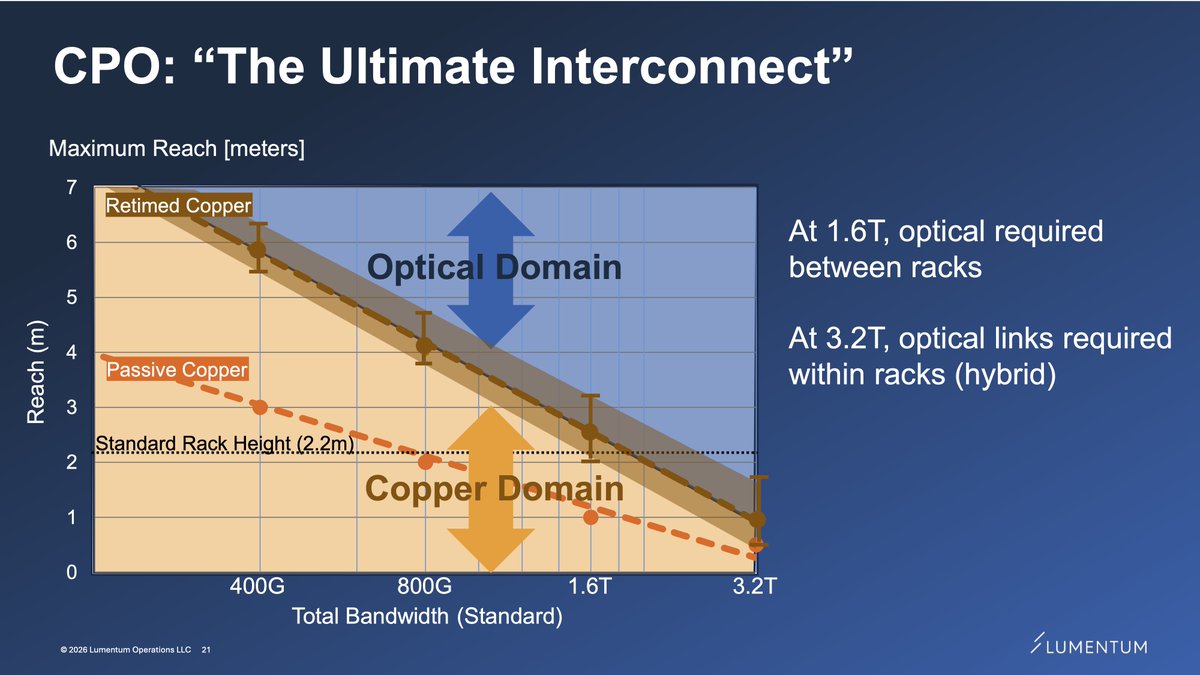
    Some things make absolute sense, like the gradual replacement of copper by optics in the backplane of equipment racks. We’re in a climate, however, where some of it is being rushed by one company’s agenda. Worth keeping in mind as one contemplates the very bright opportunity in front of laser suppliers such as Lumentum and Coherent. Lumentum and Nvidia push ‘scale up,’ but is it real? Nvidia’s vision for computing is supercomputers dedicated to AI. A lot rests on the fiber-optic components that Lumentum, Coherent, Broadcom and others make. It could be a big expansion of their market opportunity. Risks include the possibility that the world won’t completely accept Nvidia’s vision for everything. $LITE $COHR $NVDA thetechnologyletter.com

    → View original post on X — @tiernanraytech, 2026-03-22 12:14 UTC

  • TL20 Semiconductor Portfolio Rebalanced Up 320% in 3.5 Years
    TL20 Semiconductor Portfolio Rebalanced Up 320% in 3.5 Years

    I’ve been writing for over a decade about a semiconductor renaissance taking place. That development is building now every day, with hundreds of companies such as Google having become chip designers. This week I rebalanced the TL20 group of stocks to consider, which is up 320% in three and a half years. One of the new additions is Celestica, the principal maker of the TPU under contract with Google. Celestica is in that bunch of contract electronics manufacturers (EMS) that do an amazing job of getting by with thin margins and still generating real cash profits. In a little over 3.5 years, the TL20 is up 315% even in this tumultuous market. The TL20 rebalancing: The biggest thing since the microprocessor Whatever you think about speculative excess in AI, the fact is that we are at an historic moment in the history of computer chips, a semiconductor renaissance that has been gathering steam for years. That very profound change is sending ripples through the tech market. Nvidia is a big part of the story. Here are other ways an investor can capture the seismic shift. thetechnologyletter.com $CLS

    → View original post on X — @tiernanraytech, 2026-03-20 18:04 UTC

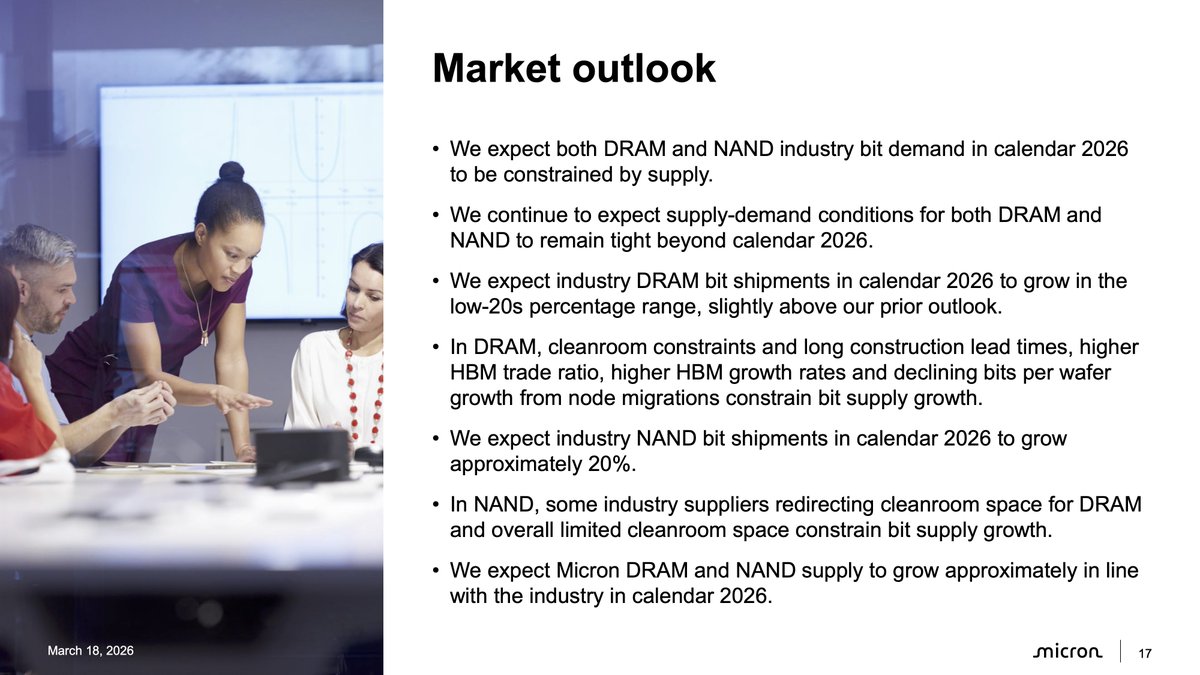
  • Micron’s Incredible Q2 Results Could Push Stock to $700
    Micron’s Incredible Q2 Results Could Push Stock to $700

    Micron could go as high as $700 as the numbers are just incredible Micron Technology turned in an astounding second-quarter report, with gross profit of seventy-five percent, and a twenty-billion-dollar-per-quarter DRAM business that is tripling. Price targets are as high as $700. And yet, people are selling on the news. The chief risk to Micron is over-supply, and Micron itself doesn’t know how much supply would be too much. Probably, over-supply risk is remote at the moment, even if it’s not zero. thetechnologyletter.com $MU $NVDA

    → View original post on X — @tiernanraytech, 2026-03-19 19:48 UTC

  • Nvidia’s Stock Stalls Despite Half-Trillion Dollar Capital Returns Plan
    Nvidia’s Stock Stalls Despite Half-Trillion Dollar Capital Returns Plan

    It’s funny because Nvidia is facing gigantic capital returns to its shareholders, but the stock is not moving. And I suspect it has something to do with the fact that nothing Jensen Huang says about AI is reassuring these days. The way he describes the It world is basically as slaves to OpenAI and Anthropic, which is depressing. He’s got to find a new narrative. Nvidia could have half-trillion in buybacks and dividends the next few years Nvidia CEO Jensen Huang used his meeting with analysts on Tuesday to emphasize a trillion dollars in orders. Equally astounding is the potential for half a trillion dollars in buybacks and dividends over the next three years that his CFO, Colette Kress, implied. Once again, though, Huang’s remarks about the AI bubble were a bit tone-deaf. thetechnologyletter.com $NVDA

    → View original post on X — @tiernanraytech, 2026-03-19 13:17 UTC

  • Adobe Needs Visionary Leadership to Compete with Canva and Figma
    Adobe Needs Visionary Leadership to Compete with Canva and Figma

    Adobe badly needs a visionary at the helm The Narayan era at Adobe was one of talking up business metrics such as “RPO” and other very dry stuff about “SaaS.” The company became trapped in that kind of language and that mindset. The problem is it no longer impresses investors, and it can’t possibly be exciting for customers. Adobe’s competitors such as Canva and Figma are doing a better job of articulating what working with AI might look like. Adobe desperately needs a visionary to show how the company will lead in an era of change. thetechnologyletter.com/the-… $ADBE

    → View original post on X — @tiernanraytech, 2026-03-13 14:13 UTC